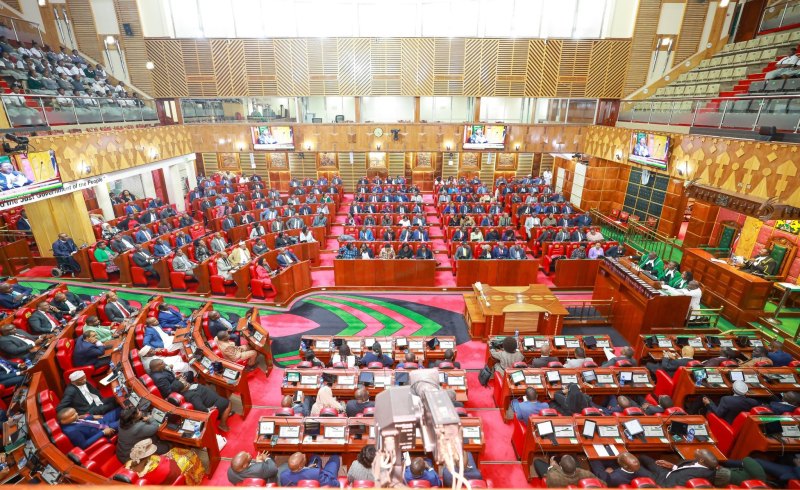
- Lawmakers are backing changes to the administrative structure overseeing Kenya’s public audit office.
- The proposed reform has renewed debate over the Auditor-General’s independence and accountability.
- The bill must pass the remaining parliamentary stages before the proposed changes can become law.
Kenya’s public finance watchdog is at the centre of a major legislative push to strengthen its independence. The National Assembly Finance Committee has joined the Senate in backing the abolition of the Audit Advisory Board, a move that could reshape how public funds are scrutinised and accounted for.
The proposed amendment to the Public Audit Act seeks to remove an administrative structure that critics argue could constrain the autonomy of the Office of the Auditor-General. This has intensified debate over how to protect the institution responsible for exposing financial irregularities and examining the use of taxpayers’ money.
The committee’s position brings the two parliamentary houses closer on the proposed reform, which targets the statutory provisions establishing the board. Supporters argue that removing the body could reduce administrative bottlenecks and give Auditor-General Nancy Gathungu greater operational freedom to manage staffing, resources and audit processes.
At the heart of the debate is the constitutional independence of the Office of the Auditor-General (OAG). It is mandated to examine public accounts and scrutinise the use of resources by national and county governments and other public entities.
Article 229 of the Constitution establishes the Auditor-General’s office and outlines its responsibility for auditing public expenditure. Article 249(2) further provides that independent offices and commissions are subject only to the Constitution and the law. They are not subject to the direction or control of any person or authority.
READ ALSO:
Proponents of the amendments argue that removing the Audit Advisory Board would bring the institution’s administrative arrangements into closer alignment with these constitutional principles. They maintain that greater operational autonomy could allow the Auditor-General to make staffing decisions, allocate resources and conduct audits with fewer administrative constraints.
The board has faced criticism over concerns that its administrative role could overlap with other oversight mechanisms and complicate the office’s decision making. However, the precise implications of abolishing it will depend on the final wording of the proposed legislation and the arrangements put in place to preserve accountability.
The reform matters because the Auditor-General plays a central role in examining whether public money is spent for its intended purposes and whether public institutions comply with financial and legal requirements. Audit reports can expose weaknesses in procurement, project implementation, expenditure management and the handling of public assets.
These findings give Parliament and county assemblies the information they need to question public officials and scrutinise government programmes. They also help lawmakers pursue corrective action where public resources have been mismanaged.
Delays in auditing public accounts can weaken timely scrutiny, while administrative restrictions may affect an institution’s ability to fulfil its mandate efficiently. Nevertheless, greater independence alone cannot guarantee accountability unless audit findings are followed by effective oversight, corrective measures and appropriate action against established wrongdoing.
The Finance Committee’s support is an important step in the legislative process, but it does not by itself mean that the board has been abolished. The Public Audit (Amendment) Bill must proceed through the applicable parliamentary stages before the proposed changes can become law. The final legislation will determine how the board’s removal affects the administration of the Auditor-General’s office and what safeguards will govern its operations.
For taxpayers, the central question is whether the proposed reform will translate into more timely audits, stronger scrutiny of public expenditure and more effective accountability for the use of public funds.
Ultimately, the success of the changes will not be measured simply by the abolition of an advisory body. It will be measured by whether Kenya’s public finance watchdog can operate independently, deliver credible audit findings and help ensure that every shilling collected from taxpayers is accounted for.
By Hillary Muhalya
Get more stories from our website: Sacco Review.
For comments and clarifications, write to: Saccoreview@
Kindly follow us via our social media pages on Facebook: Sacco Review Newspaper for timely updates
Stay ahead of the pack! Grab the latest Sacco Review newspaper!